What is the market overview and scope of the Cellular Reprogramming Anti-Aging Therapeutic Market?
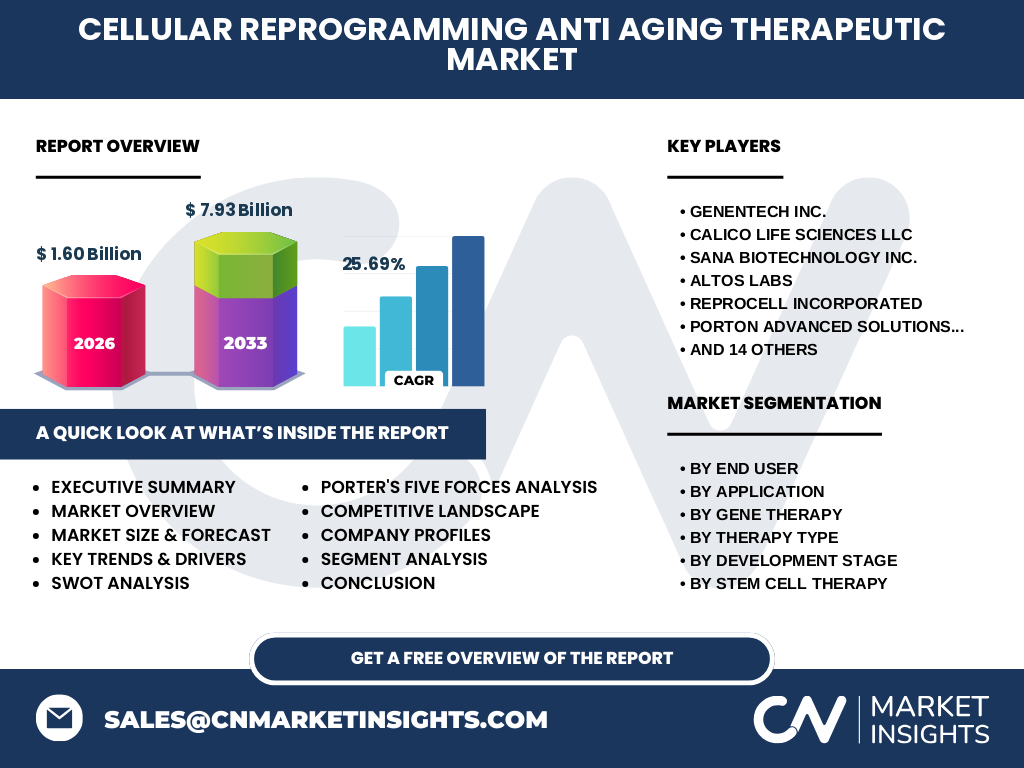
Our analysis indicates that the Cellular Reprogramming Anti-Aging Therapeutic Market represents a paradigm shift in regenerative medicine, valued at $1.60 Billion in 2026. This sector encompasses advanced therapies designed to reverse cellular senescence by resetting epigenetic clocks. Market significance lies in its potential to treat age-related degeneration at the root molecular level, moving past mere symptom management.
Structural Growth Drivers and Restraints
The Cellular Reprogramming Anti-Aging Therapeutic Market industry trends are heavily propelled by surging venture capital investments in epigenetic rejuvenation and rising geriatric demographics. However, our research highlights severe growth restraints, including complex FDA and EMA regulatory hurdles for novel gene-based interventions, and immunological safety risks such as teratoma formation linked to induced pluripotent stem cells.
Emerging Trends and Growth Patterns in Cellular Reprogramming Anti-Aging Therapeutic Market
The market is witnessing a profound shift toward non-integrative delivery mechanisms and transient mRNA transfection to avoid permanent genomic alterations. Industry leaders are aggressively combining artificial intelligence with high-throughput screening to identify potent senescence-modulating small molecules, fundamentally accelerating preclinical candidate selection across major biotech hubs.
How did COVID-19 impact the Cellular Reprogramming Anti-Aging Therapeutic Market?
The pandemic temporarily disrupted clinical trial recruitment and strained supply chains for viral vector raw materials. Yet, our analysis shows that the crisis ultimately accelerated the Cellular Reprogramming Anti-Aging Therapeutic Market recovery by validating lipid nanoparticle mRNA delivery platforms, paving the way for rapid translation of cellular rejuvenation therapies into human trials.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is defined by aggressive intellectual property acquisition among pioneering startups like Altos Labs, Retro Biosciences, and Life Biosciences. Market concentration remains moderate as venture-backed entities partner with specialized contract development and manufacturing organizations such as Porton Advanced Solutions Ltd. and uBriGene Biosciences to secure scalable clinical-grade viral and non-viral vectors.
Executive Summary of the Cellular Reprogramming Anti-Aging Therapeutic Market
Our comprehensive evaluation confirms that the Cellular Reprogramming Anti-Aging Therapeutic Market is primed for explosive expansion, scaling from $1.60 Billion in 2026 to $7.93 Billion by 2033 at a remarkable CAGR of 25.69%. This trajectory underscores a major commercial transition from academic longevity research to heavily funded clinical-stage therapeutic pipelines addressing age-related chronic pathologies.
Market Forecast Analysis (2027 to 2033)
Driven by maturing clinical pipelines transitioning from Phase I to Phase II trials, the Cellular Reprogramming Anti-Aging Therapeutic Market size will experience accelerated compounding growth. Based on our research, the 25.69% CAGR will be sustained by breakthrough approvals in ophthalmological aging and neurodegenerative disorder applications, unlocking multibillion-dollar commercial value by 2033.
Segmentation Analysis Across Applications and Therapies
Market segmentation spans critical therapeutic areas including cardiovascular disorders, neurodegenerative diseases, and ophthalmological aging. Therapy types are categorized across gene therapy, epigenetic reprogramming, and messenger ribonucleic acid based cellular reprogramming. End users are heavily concentrated in specialized regenerative medicine clinics, hospitals, and biotechnology companies driving clinical translation.
Regional Market Analysis and Geographic Performance
Geographic distribution heavily favors North America, anchored by robust venture capital ecosystems and progressive FDA regenerative medicine frameworks. Meanwhile, the Asia-Pacific region is emerging as a formidable manufacturing and clinical trial powerhouse, supported by proactive regional regulatory bodies in Japan and supportive bioclusters in South Korea involving firms like HanAll BioPharma Co. Ltd.
In-Depth Regional Review
North America dominates the Cellular Reprogramming Anti-Aging Therapeutic Market due to dense clusters of longevity biotechs in Boston and the San Francisco Bay Area. Concurrently, Europe exhibits steady growth constrained by stringent EMA oversight, while Asia-Pacific accelerates via expedited regenerative medicine pathways that favor rapid clinical validation of stem cell and gene therapies.
Strategic Positioning of Leading Companies
Industry participants deploy distinct strategic plays: Genentech Inc. and Calico Life Sciences leverage deep pharmaceutical partnerships, whereas focused innovators like Turn Biotechnologies, Cellino Biotech Inc., and Shift Bioscience Ltd. utilize proprietary mRNA delivery and automated cell processing technologies to outpace legacy biopharma in epigenetic rejuvenation.
Porter's Five Forces Analysis
The threat of new entrants is moderate due to prohibitive R&D costs and stringent regulatory barriers, though agile startups constantly disrupt the baseline. Buyer power is low given the high unmet medical need in aging-associated chronic diseases, while supplier power over critical viral vectors and lipid raw materials remains notably high.
SWOT Analysis of the Industry
Key strengths include unprecedented scientific breakthroughs in epigenetic reset mechanisms, while weaknesses involve complex in vivo delivery hurdles. Opportunities abound in untapable dermatological aging and metabolic disorders, weighed against threats of premature clinical translation and uncertain long-term oncological safety profiles.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing high-purity nucleotides and plasmid DNA, flowing through specialized contract manufacturers like Porton Advanced Solutions Ltd. for vector production. It culminates in clinical research organizations and hospitals administering injectable, topical, or intravenous therapies to patients suffering from degenerative conditions.
Investment Insights and High-Potential Areas
Our analysis indicates that investors should prioritize platforms featuring transient, non-integrating delivery modalities such as lipid nanoparticle mRNA and targeted small molecule therapy. Companies developing scalable, automated manufacturing systems for induced pluripotent stem cells represent prime targets for venture allocation given current clinical bottlenecks.
Conclusion and Key Takeaways
The Cellular Reprogramming Anti-Aging Therapeutic Market is transitioning from theoretical longevity science to a validated clinical reality. With a projected $7.93 Billion valuation by 2033, stakeholders must navigate rigorous regulatory pathways and manufacturing complexities to capture immense value in reversing biological age.
Research Methodology
Our data triangulation methodology combines exhaustive trade registry data, primary qualitative interviews with C-level executives across firms like Sana Biotechnology and Altos Labs, and secondary macroeconomic indicators. Baseline estimates for 2026 are cross-referenced against clinical trial registries and venture capital funding disclosures to ensure absolute analytical rigor.
Scope of the Report and Limitations
This report covers global market dynamics for the Cellular Reprogramming Anti-Aging Therapeutic Market from 2027 to 2033, analyzing segments across development stages from preclinical to Phase II. Limitations include unpredictable shifts in global regulatory approvals and the proprietary nature of early-stage stealth biotechnology startup pipelines.
Recent Developments and Strategic Industry Moves
Recent milestones feature aggressive capital raises, strategic licensing agreements, and patent acquisitions by pioneers such as Retro Biosciences and NewLimit Inc. Furthermore, collaborations between clinical research organizations and vector manufacturers are rapidly streamlining the supply chain required to support escalating Phase I and Phase II trial volumes.